Brian Williams · Move Real Estate · Portland, Oregon
I spent eight years originating these loans. Now I'm on your side of the table.
Almost nothing that goes wrong in a home purchase is a surprise. Buyers get blindsided by the same eight or nine things, over and over, and every one of them is preventable with information you could have had for free three months earlier.
I was a mortgage loan officer for eight years before I became a REALTOR®. I've watched this fall apart from both directions. Here's the pattern I see over and over: buyers save diligently for a down payment, hit their number, and find out at closing that it was maybe half the cash they actually needed. That chapter is free.
Free guide · 8 pages
Mortgage Ready
How much money you need to buy a home. The money chapter from the book, given away, plus the full document checklist and three things to do this week. No card.
8-page PDF · instant download, and a copy by email
Want the whole book?
All 11 chapters + both worksheets — $19
You're in
It's ready.
Download it right now, and I've emailed you a copy so you don't lose it. If it isn't in your inbox in two minutes, check promotions.
↓Mortgage ReadyPDF · 8 pagesDemo — nothing was submitted
While you're here
The other ten chapters — and both worksheets
You now know what the money costs. The book adds how lenders actually see you, the escrow trick that makes one quote look cheaper than it is, writing an offer that wins, and the ten things that kill a loan after you're approved. Plus the fillable cash-to-close and lender comparison worksheets.
Or read the free guide first. It'll still be here.
If you've said any of these out loud in the last month, this was written for you.
"We have the down payment saved. That's most of it, right?"
"Everyone says you need 20% down."
"What's the actual difference between pre-qualified and pre-approved?"
"Three lenders quoted me. One is way cheaper. I'm going with that one."
"Everyone says waive the inspection or you won't get the house."
"We're under contract. Can we buy the couch now, or wait?"
"I signed something with an agent. I'm not sure what it said."
"We got outbid four times and I don't know what we did wrong."
The down payment is not the finish line.
Buyers budget for the down payment and forget the other three buckets. Inspections come out of pocket in the first ten days whether or not you buy the house. Closing costs and prepaids land on top at the table. Reserves come after. Drag the price to see the gap.
What you budgeted
$22,500
Cash to close
$36,000
$13,500 short
Before inspections and move-in. With those, you're $19,775 short.
Under 20% down, so conventional PMI applies — but it comes off at 78% LTV, which is the whole conventional-vs-FHA question. Chapter 4.
Illustration only, using the worked example from Chapter 3 and Portland-area inspection pricing. Closing costs commonly run 2–5% of the price — 3% is used here, including prepaids and escrow setup — and vary widely by state, lender, and loan size. Earnest money is commonly 1–3%, is negotiable, and is set by your contract; it is part of your down payment, not an extra cost. Your Loan Estimate is the only number that counts. Not a loan approval, a commitment to lend, or a quote.
Why the cheaper quote can sometimes be deceiving.
Nobody Told Me That · Chapter 4
A lender can quote three months of property taxes when the file will actually require seven, and their “cash to close” comes out thousands lower than the honest quote sitting next to it. It looks like the better deal. It isn't.
Unlike origination charges and points — which are locked in tight once a Loan Estimate is issued and locked — escrow and prepaid estimates have no tolerance limits. A lender can be wildly optimistic there and face no consequence for it.
I lost deals over this as a loan officer and buyers were left with an unpleasant surprise. I'd give someone an honest quote collecting the correct number of months, a competitor would come in short, and the buyer would go with the lower cash-to-close number — which is a completely rational thing to do when you're comparing two documents that appear to be measuring the same thing. Then, roughly thirty days later, I'd get the phone call.
Chapter 4 has the full section: the exact question to ask every lender, and how to normalize a comparison so the quotes differ only where they should. The lender comparison worksheet turns it into a form you fill in.
Eleven chapters, in the order the transaction happens.
Every chapter ends with The Short Version, a summary you can act on if that is all you read. A whole industry of 300-page homebuying books could have been 35 pages. This is the 35.
Are You Actually Ready?
The seven readiness signals, and the Payment Shock Test, which tells you in 90 days whether the payment is livable. It costs nothing to run.
How a Lender Actually Sees You
The Four Cs, from the other side of the desk. Paying off one small car loan often buys more house than another $10,000 saved.
The Money You Actually Need Free
The four buckets: inspections, down payment, closing costs, reserves. Where earnest money fits, and the $13,500 nobody budgets for.
Loan Programs, Decoded
Conventional, FHA, VA and USDA, points and buydowns, and why “Veterans” in a lender's name tells you nothing. How to compare lenders when one is padding the escrow line.
Pre-Approval, The Right Way
Pre-qualified, pre-approved and underwritten mean three different things, and the third one wins houses. When to shop lenders, and the four steps that make them compete for your loan.
Your Team (And Who Pays Whom)
What the 2024 compensation rules changed. Show up for the last 45 minutes of the inspection, not the first.
The Search
Five needs, everything else is a want. What costs money to change. How to read a listing, and where the flaw hides in the photos.
Writing an Offer That Wins
Compete on terms as well as price. Capped appraisal gaps instead of blanket waivers. The as-is offer that keeps your exit.
Under Contract: The 30-to-45-Day Sprint
Week by week. Your protections expire on schedule. Read the wire fraud section twice.
The Deal-Killers
The Ten Commandments of being under contract. Every year, somebody loses a house over a couch.
Closing Day and the First 90 Days
You skip a month before your first payment. Use that gap when you time your lease.
Two worksheets that do the arithmetic you'd otherwise do wrong.
Each comes two ways. Fill in the yellow cells of the Excel version and it does the arithmetic as you type. The fillable PDF works on any device, and prints for the lender's office.
Cash-to-Close Builder
Enter a price and a down payment percentage. It builds your real number, including the money people forget, then nets out seller concessions, lender credit, and down payment assistance.
Your shortfall, in months
Enter what you've saved and what you can save monthly. It tells you the gap and how many months of saving it takes to close it. That turns "someday" into a date.
Lender Comparison
Built to match sections A through J of a real Loan Estimate, straight off page 2. Line up three lenders and see which quote is cheaper and which one looks that way.
Months of escrow collected
The one row where a lender can massage a quote. Compare the months of property taxes collected and the annual tax figure used. Same house, same taxes. If they differ, one lender has it wrong.
Start with the money. Buy the rest if it earns it.
The free guide is the money chapter pulled straight out of the book, plus the full document checklist. You need it before you start looking. Read it, run your own numbers, and you will shop against a real target instead of a myth.
Mortgage Ready
Free · 8 pp.
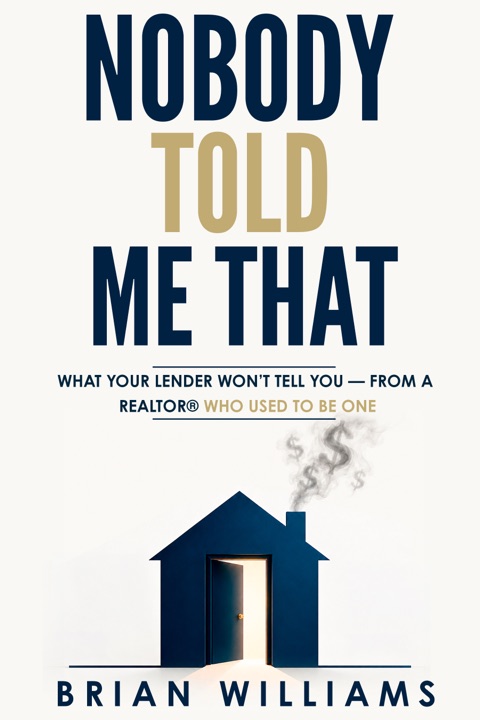
Nobody Told Me That
$19 · 37 pp.

Brian Williams, REALTOR®
Move Real Estate · Portland, Oregon
Buying in the Portland metro? Bring me your Loan Estimate.
The book is national on purpose. Loan mechanics, offer strategy and the federal disclosures work anywhere. Your county does not. Underground oil tanks, cesspools, radon, and sewer lines in our older housing stock are Portland problems, and they're expensive after the fact.
Fifteen minutes, no pitch, no obligation to use me as your agent. If you already have one, bring their name and I will tell you what I know. Buying outside Oregon, I will connect you with someone I trust.
Buyer strategy call
Or reach me directly
541-579-6342 · brianw@moverealestate.org
Before you download.
Is the free guide actually free?
What's the difference between the guide and the book?
Is this useful outside Oregon?
You were a loan officer. Are you selling me a loan?
I already have an agent. Still worth reading?
How current is it?
Can I get a refund?
The four buckets, before you talk to a single lender.
The buyer who saves 5% down and stops is about $13,500 short on a $450,000 house. That's the chapter, and it's free. If it's useful, the other ten are $19.
Free guide · 8 pages
Mortgage Ready
The money chapter, the document checklist, and three things to do this week.
8-page PDF · instant download, and a copy by email
You're in
It's ready.
Download it now. A copy is on its way to your inbox too.
↓Mortgage ReadyPDF · 8 pagesDemo — not actually submitted
Ready for the rest?
The full book — $19